- Total Till sales grew +3.2% in the four weeks ending 31st October, as Halloween, half-term and grocery stock-ups helped lift spending.
- Ambient grocery sales surged +10.6% in the final two weeks, while Halloween celebrations boosted demand for confectionery, snacks and pumpkins.
- Online grocery drives the majority of FMCG growth, contributing nearly 59% of value growth and 80% of unit growth.
Total Till sales at UK major supermarkets increased by +3.2% in the four weeks ending 31st October 2026, according to the latest data released today by NielsenIQ (NIQ).
NIQ data shows that sales momentum strengthened throughout October, with growth reaching +4.1% in the final week of the month. This helped drive unit sales growth to +1.5% over the four-week period, the strongest performance recorded this year outside of Easter. 1
The latest data also shows the frequency of shopping increased (+2.1%) compared with last year, while the average spend per visit rose (+1.5%) to £18.96. 2 This came as food inflation increased to +2.9% in October, up from +2.4% in September. 3
Canned goods drive category growth
Ambient grocery was the fastest-growing supermarket super-category in October, with sales up +6.9%. Growth gathered pace as the month progressed, rising from +3.3% in the first fortnight to +10.6% in the second.
Canned goods, within ambient grocery, surged +27% in the second half on the month. This coincided with the Be Ready government advice, which may have contributed to changing grocery shopping patterns. 1
Halloween provides an Autumnal boost
The recovery in Total Till sales emerges despite weakening consumer confidence which fell 11 points to -24. The last time we saw a drop of this size was following the Brexit vote. 4 Rising energy and fuel costs are also continuing to put pressure on household budgets. While shoppers remained mindful of their spending, the half-term holidays and Halloween provided a welcome boost for supermarkets, as families embraced seasonal celebrations while continuing to seek value.
Pumpkins were a standout seasonal purchase, with unit sales growing +8% year on year highlighting the importance of affordability in encouraging Halloween spending. 1
The impulse super-category recorded value growth (+5.4%), supported by demand for sweets, chocolate sharing multipacks and snacks. While the value sales of multipack confectionery were broadly flat (-0.5%), unit sales increased (+4.5%), suggesting shoppers were buying more packs without a corresponding increase in spend. 1
Elsewhere, alcoholic ready-to-drink beverages (RTDs) recorded strong value growth of +28%, despite overall alcohol sales remaining largely flat (+0.1%). Cosmetics sales also increased +3.5%, although some categories traditionally associated with Halloween failed to grow compared with last year, suggesting shoppers continued to make selective trade-offs on discretionary purchases. 1
Online grocery accelerates as shoppers embrace rapid delivery
Online grocery continued to outperform the wider market in October, with ecommerce sales increasing +13.1%, compared with growth of just +1.5% for in-store sales. 5
NIQ data shows that ecommerce accounted for almost 59% of all FMCG value growth at the major supermarkets and 80% of incremental unit growth, underlining the growing importance of online shopping as households replenished grocery supplies.
Online also benefited from the Halloween demand, particularly in categories such as confectionery, as shoppers turned to digital channels for seasonal treats and last-minute purchases.
Rapid grocery delivery saw strong growth, accounting for +11.5% of all online FMCG sales on Saturday 31st October, reaching levels comparable with the highs seen during the summer months. 6
Tesco gains momentum as Ocado, M&S and Lidl outperform
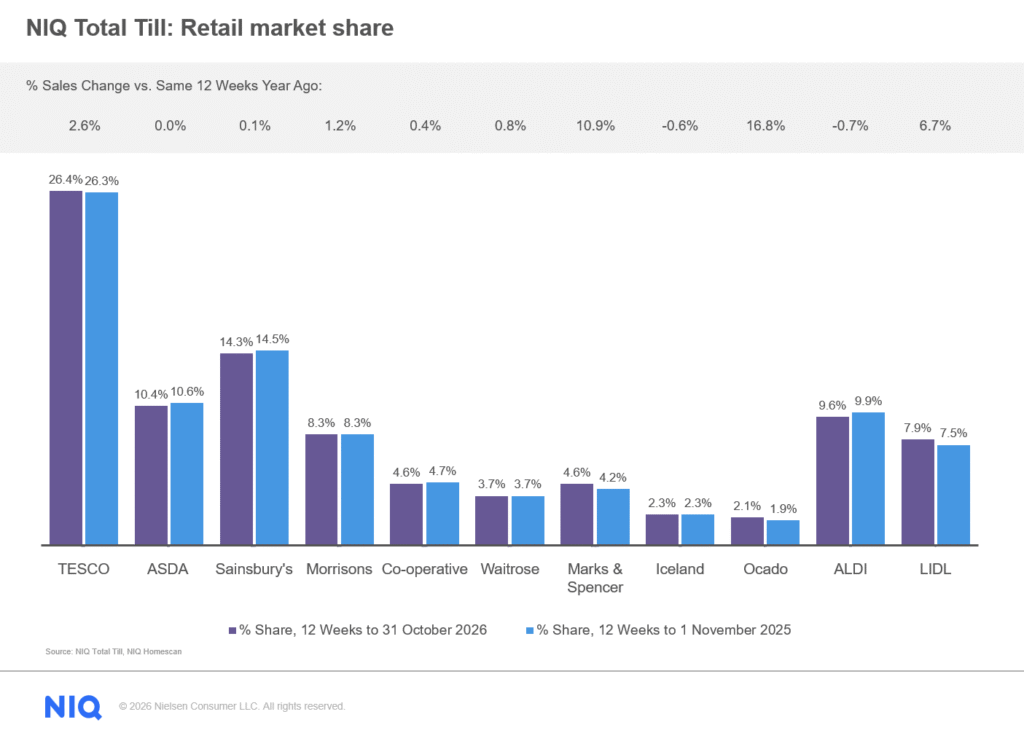
In terms of retailer performance, Tesco gained momentum, with sales increasing +2.6% over the latest 12 weeks, ahead of Morrisons (+1.2%). Meanwhile, sales at Sainsbury’s and Asda were broadly flat over the same period.
Ocado (+16.8%) and M&S (+10.9%) continued to deliver double-digit growth, significantly outperforming the wider market, while Lidl also recorded strong sales growth of +6.7%.
The latest figures suggest that retailers offering a compelling combination of value, convenience and differentiated products remain well placed to capture shopper spending as the industry moves into the crucial festive trading period.
Mike Watkins, Head of Retailer and Business Insight at NielsenIQ, said: “There was improved growth in supermarket sales in October, helped by the half-term holidays and Halloween, which encouraged shoppers to spend more on special treats for the family. This is despite consumer confidence falling, suggesting shoppers are still willing to loosen the purse strings when there’s an occasion to celebrate.”
Watkins concluded: “Looking ahead, the industry needs to get shoppers in the mood to spend, so the launch of Christmas advertising campaigns will be important in showcasing what’s new, different, and, crucially, affordable. With Black Friday providing another focus for shoppers in November, we expect the acceleration in supermarket sales to begin in early December. Given the current momentum, we anticipate Total Till growth of around +2.5% to +3% this Christmas, as retailers look to make the most of the crucial final weeks of the year.”
 Unless otherwise stated all data is NIQ Homescan Total Till
1 NIQ Scantrack, Total Coverage
2 NIQ Homescan Consumer Panel
3 BRC-NIQ Shop Price Monitor
4 GfK Consumer Confidence Barometer
5 NIQ Scantrack eCommerce Defined Grocery Multiples
6 NIQ Digital Purchases
Comments are closed.